
Login to track your progress, bookmark questions, and view history.
Q#1
Random Variable and Random Process
GATE EC 2025
MCQ
+2 marks
-0.66 marks
Consider a real-valued random process
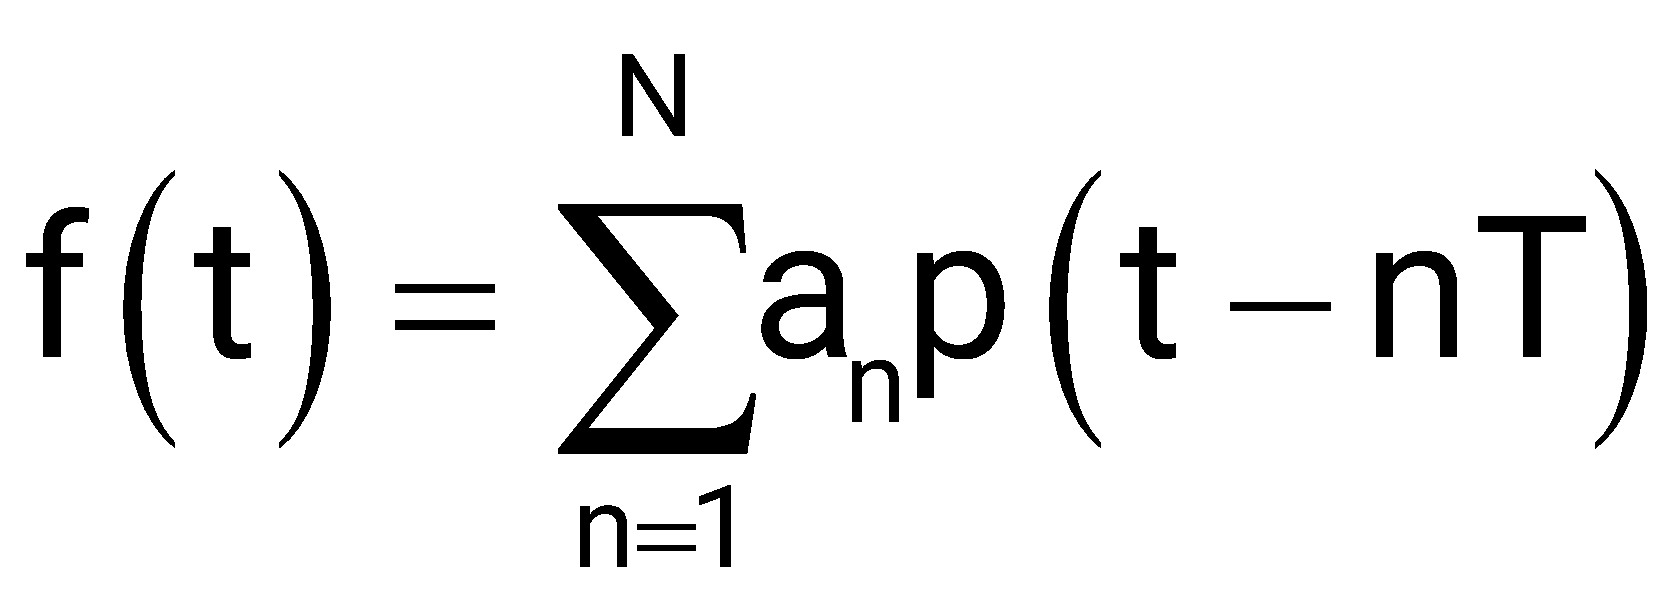
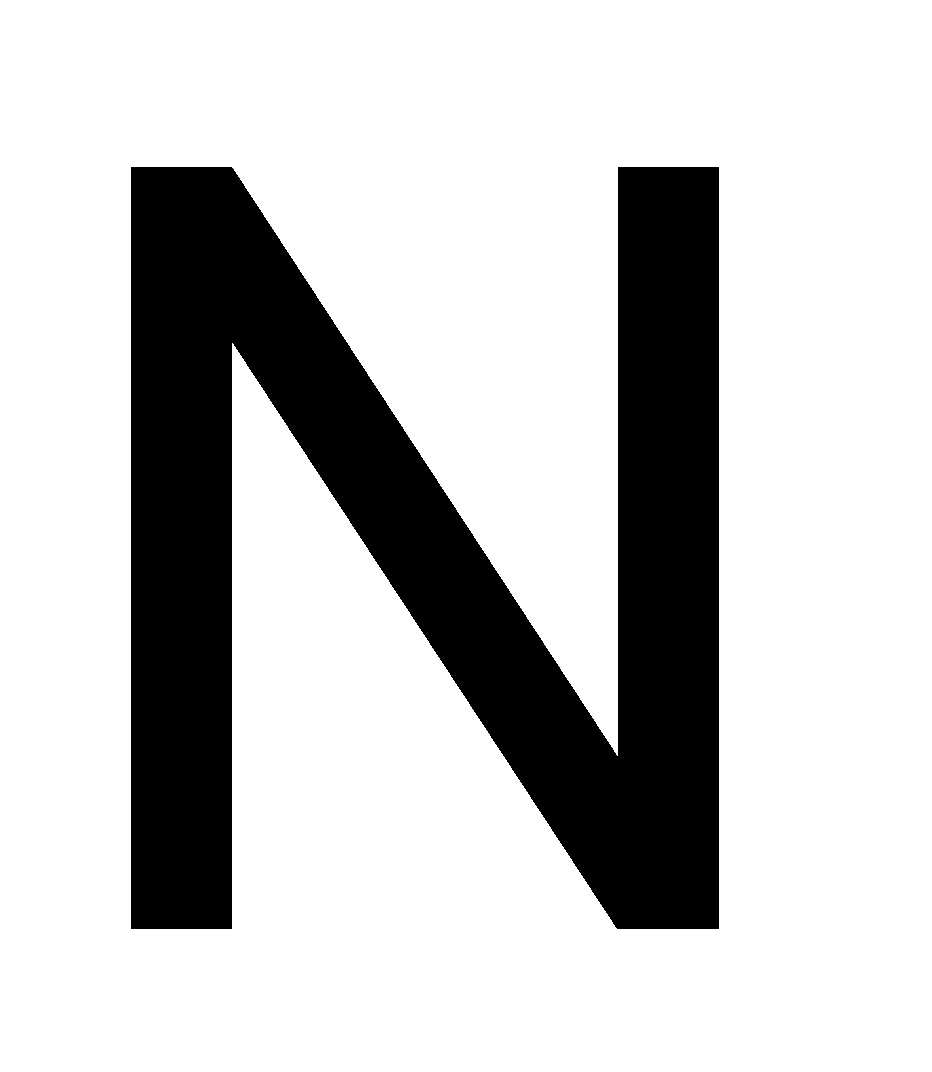
where and is a positive integer. Here, for and 0 otherwise. The coefficients are pairwise independent, zero-mean unit variance random variables.
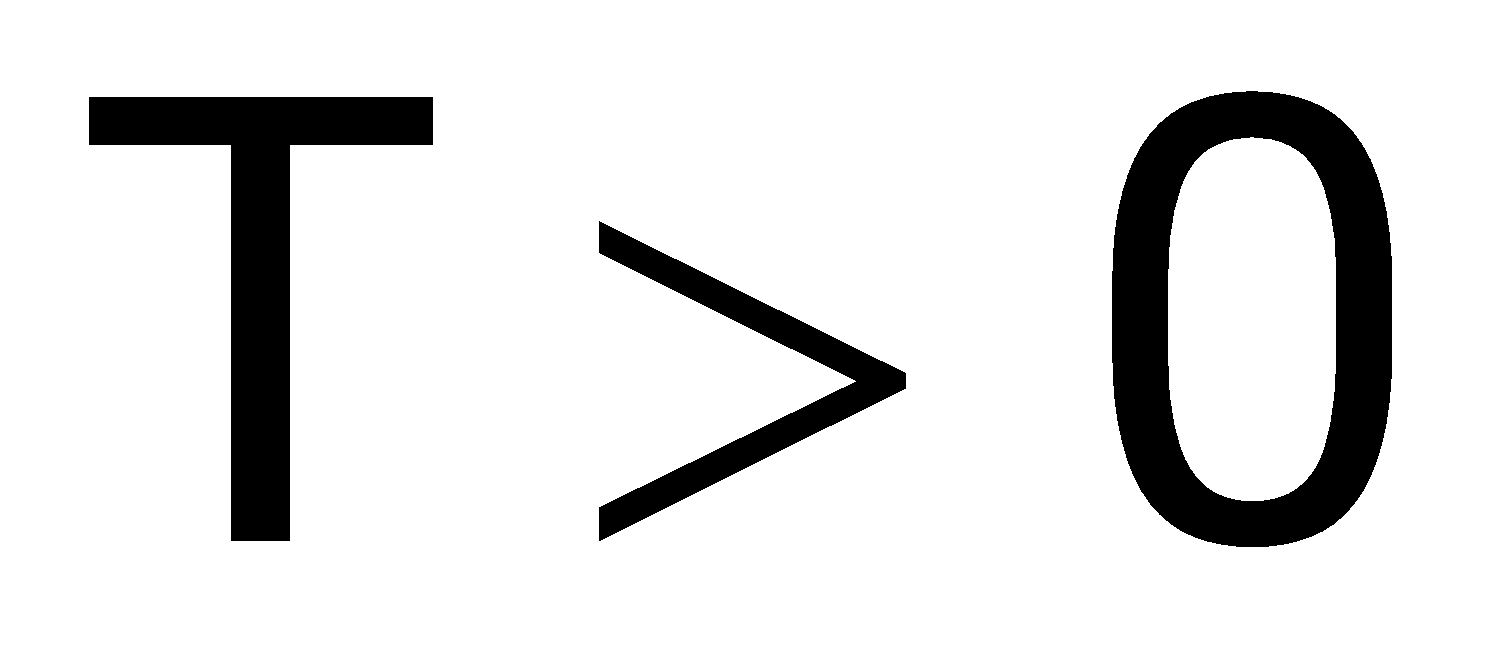
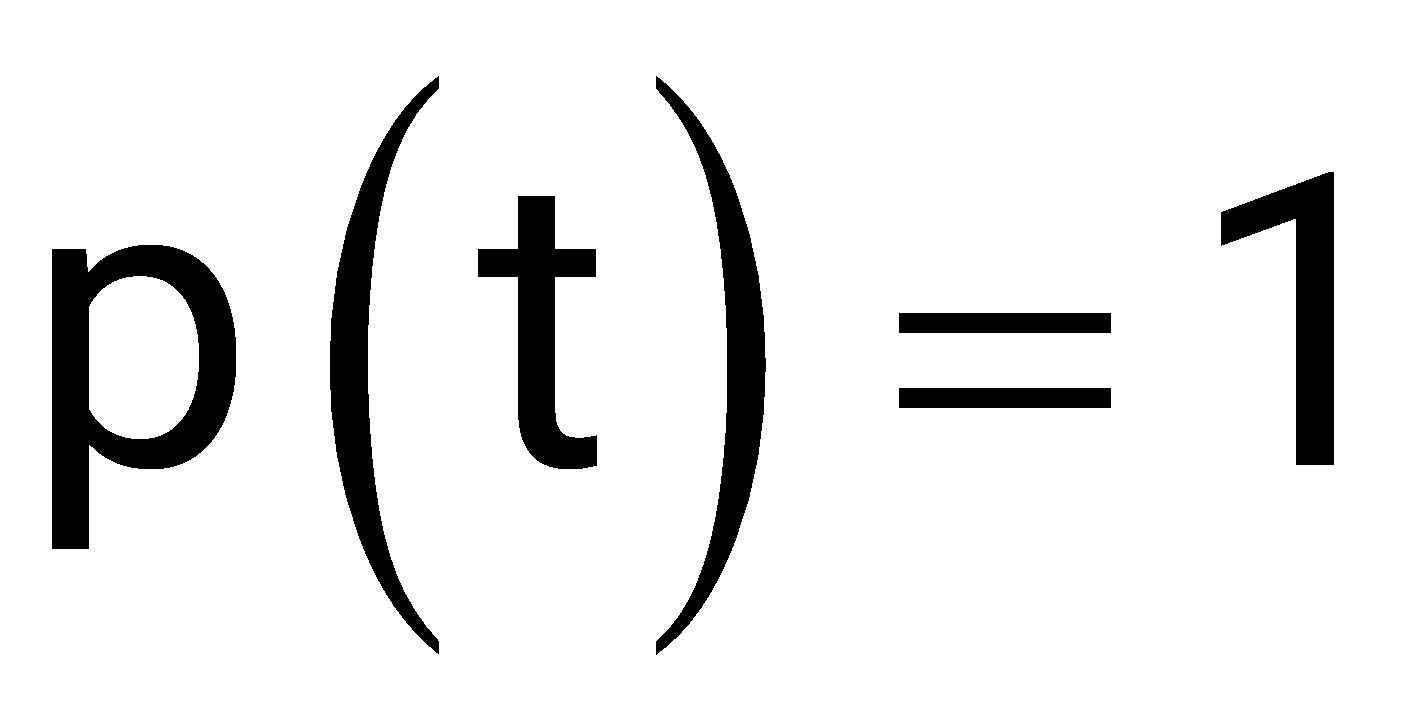
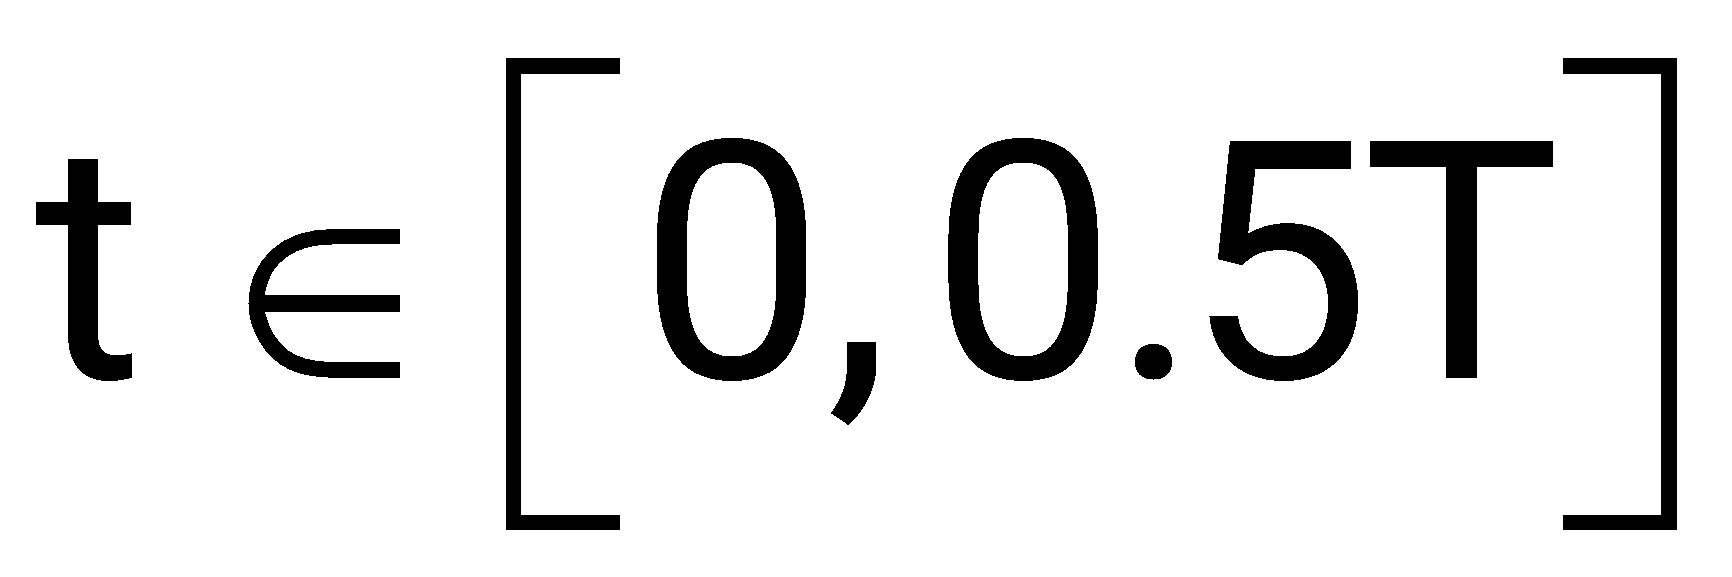
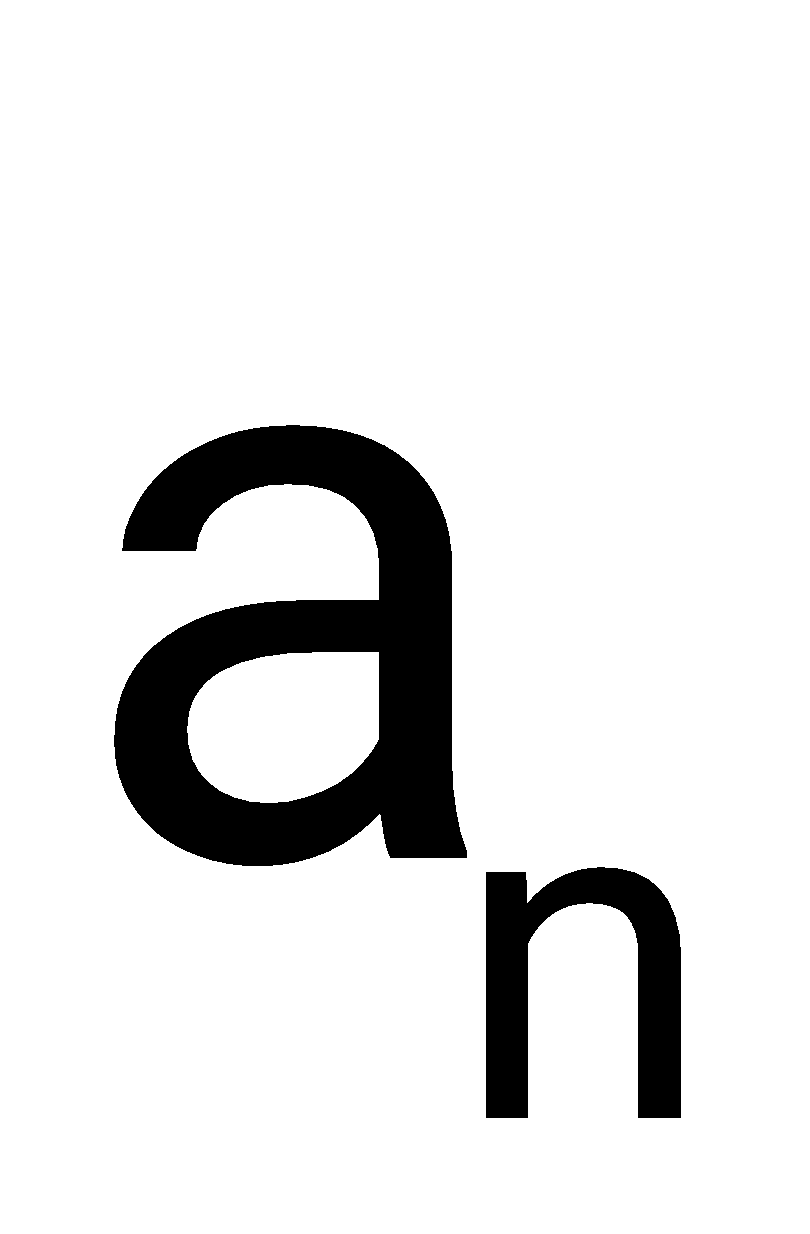
Read the following statements about the random process and choose the correct option.
(i) The mean of the process is independent of time .
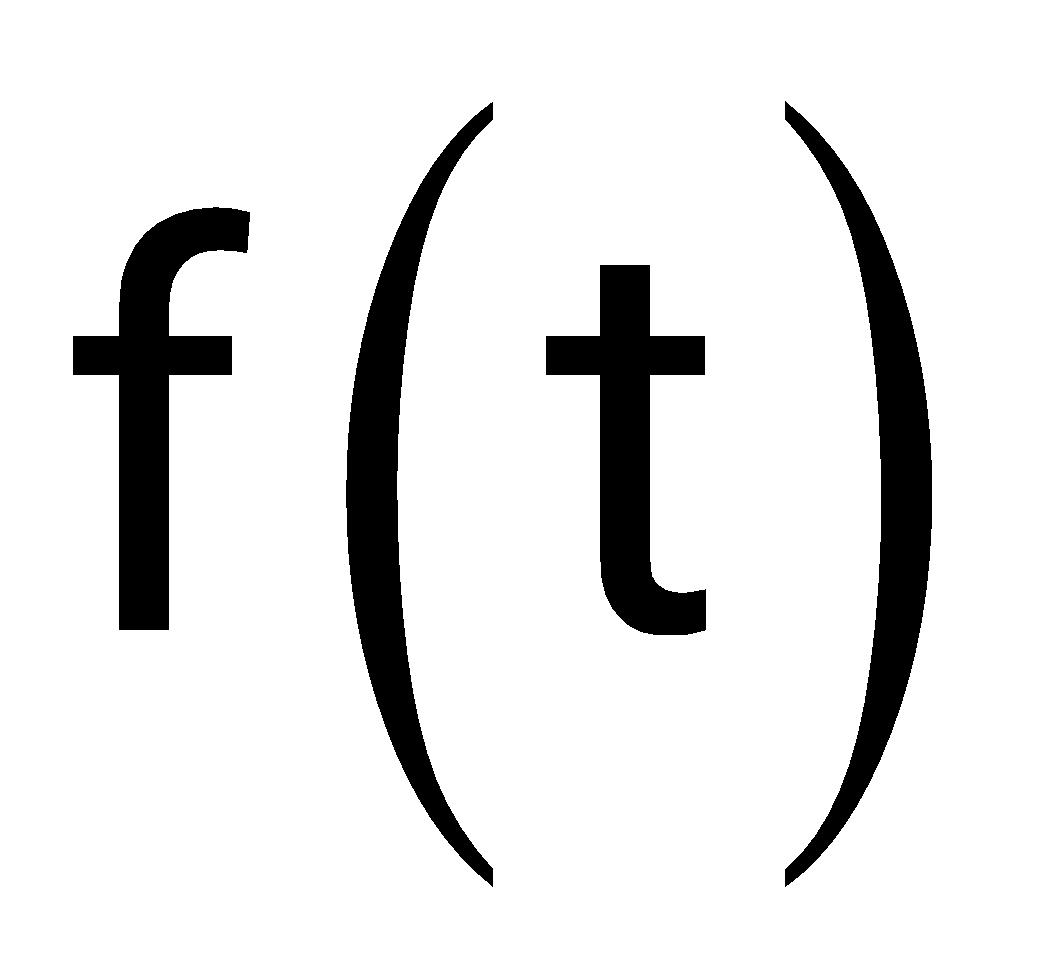
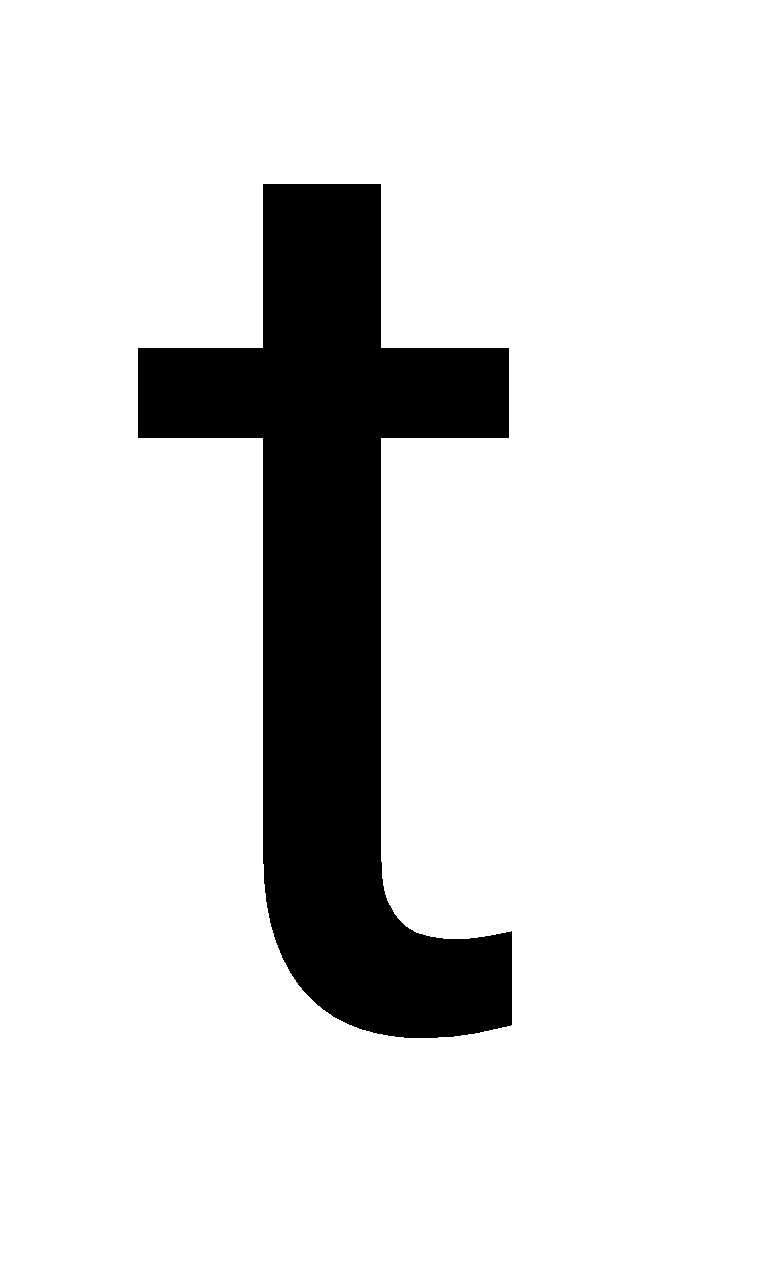
(ii) The autocorrelation function is independent of time for all .
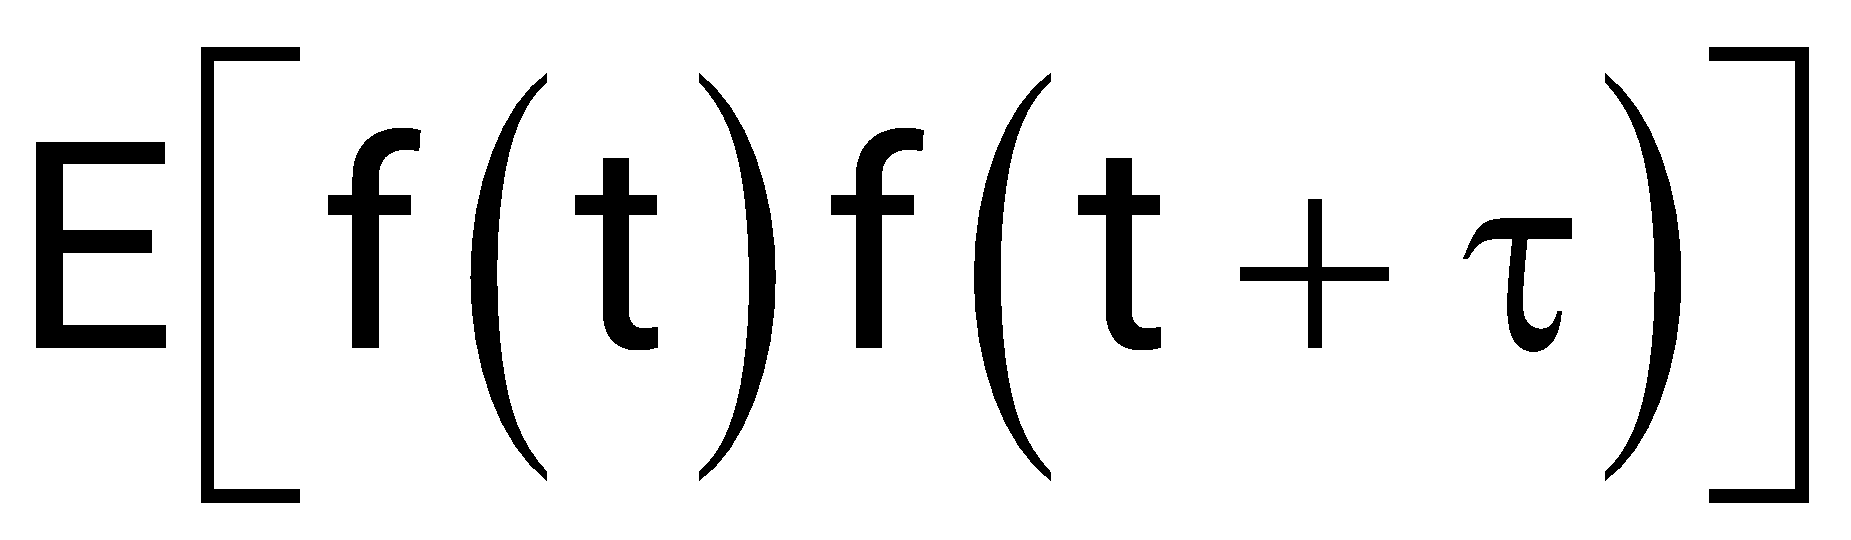
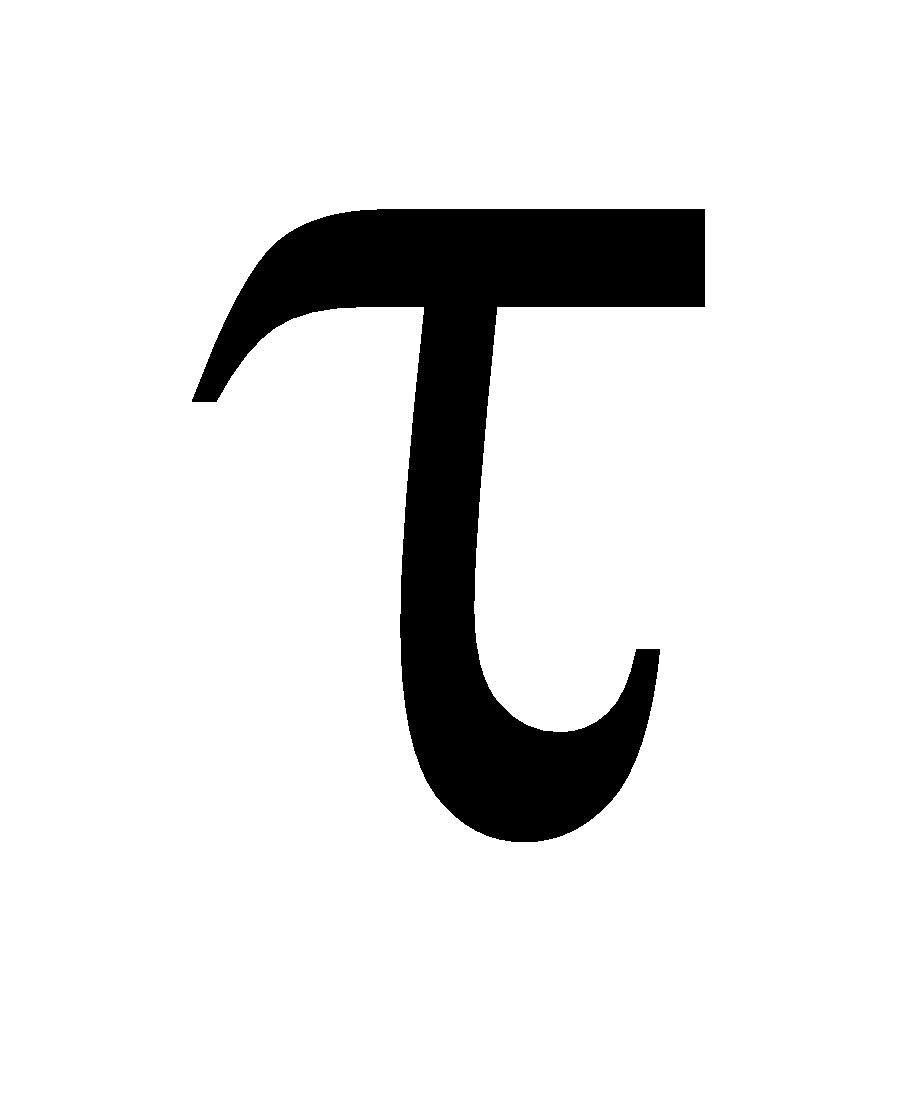
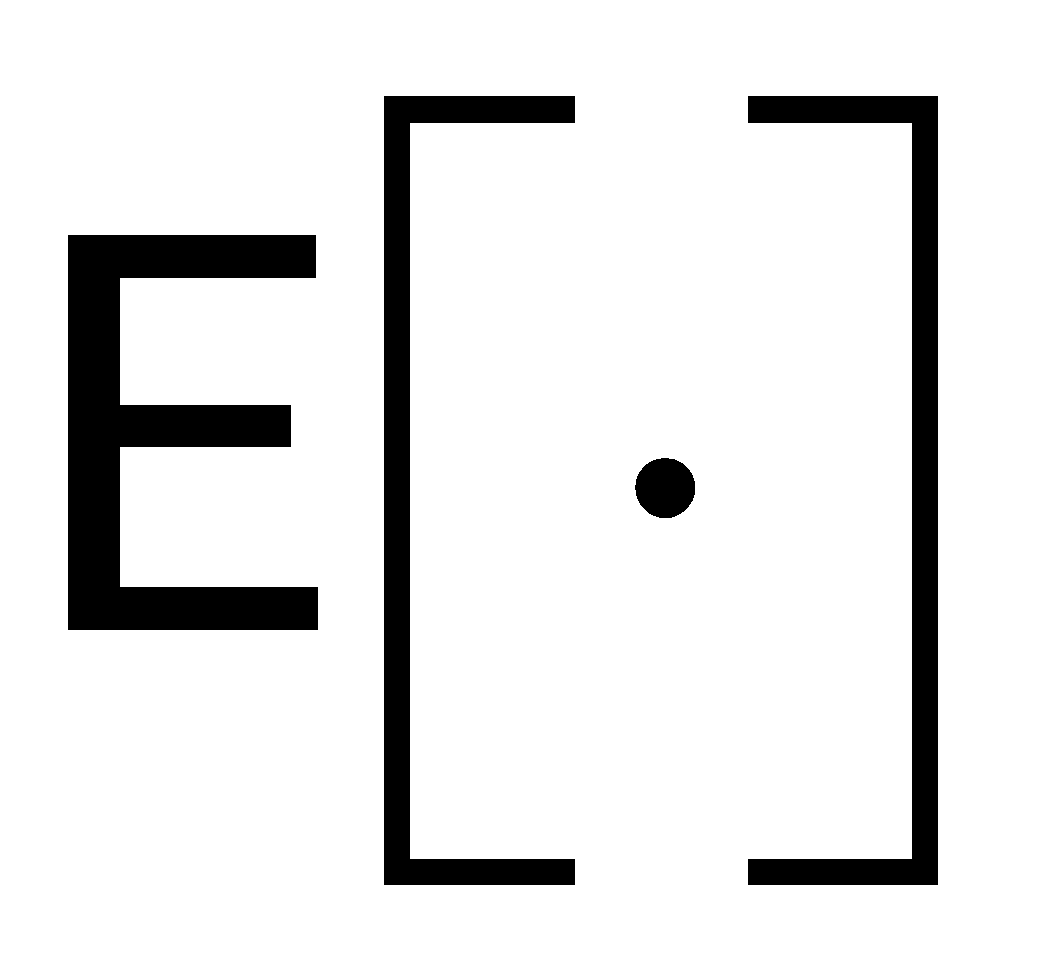
(Here, is the expectation operation.)
Sign in to see the solution
Log in to view the explanation, track your attempts, and keep your progress.
Sign in to Unlock
Login to keep track of your progress with the tool with daily goals, questions preparation and more.
Browse Practice Questions by Chapters / Topics in Browse Practice Questions by Chapters / Topics in GATE Electronics and Communications
Total Questions
Attempted
% Attempted
Correct
% Correct
Login to keep track of your progress with the tool with daily goals, questions preparation and more.
| Topic | Questions | Attempted | Correct | |
|---|---|---|---|---|
| Network Analysis | 273 | 0 | 0 | |
| Electronic Devices | 69 | 0 | 0 | |
| Analog Electronics | 395 | 0 | 0 | |
| Digital Electronics | 351 | 0 | 0 | |
| Signals and Systems | 22 | 0 | 0 | |
| Control Systems | 224 | 0 | 0 | |
| Communication System | 200 | 0 | 0 | |
| EMFT - ECE | 14 | 0 | 0 | |
| Engineering Mathematics | 24 | 0 | 0 | |
| General Aptitude | 30 | 0 | 0 |